Microsoft Stock at $498: The AI Rally Gap, and What Closes…
Updated 23 September 2026, 14:00 UTC
Microsoft (NASDAQ: MSFT): $498.00, down $3.61 or 0.72% at the 22 September close, after trading as high as $508.50 and as low as $493.65 that session. The stock was quoted at $503.00, up 1.00%, in pre-market trading at 9:08 a.m. ET on 23 September (StockAnalysis).
Verdict: The Nasdaq-100 has printed back-to-back record closes and Microsoft has not been part of either one. On 21 September the index rose 2.83% and Microsoft managed 1.59%; on 22 September the index rose 0.82% to a record and Microsoft fell. The gap is not a mystery – it is the market marking down a company that is spending an extraordinary amount of cash today for revenue that arrives later.
Key facts
- Microsoft is not leading the AI rally it is supposed to lead. The Nasdaq-100 closed at 30,482.35 on 21 September, up 2.83%, while Microsoft rose 1.59% to $501.61. The next session the index added 0.82% to a record 30,732.40 and Microsoft fell 0.72% to $498.00 (Nasdaq index data; StockAnalysis).
- The underperformance is a year-long pattern, not a two-day one. Microsoft is up roughly 3% in 2026 against an S&P 500 up 11.3% as of 11 September – a lag of about 900 basis points – and is down 2.08% over the past twelve months (24/7 Wall St., 21 September).
- The business is not the problem. Azure grew 43% year over year in fiscal Q4 2026, guidance for fiscal Q1 2027 is roughly 45% in constant currency, and Azure’s annual revenue has crossed $100bn for the first time.
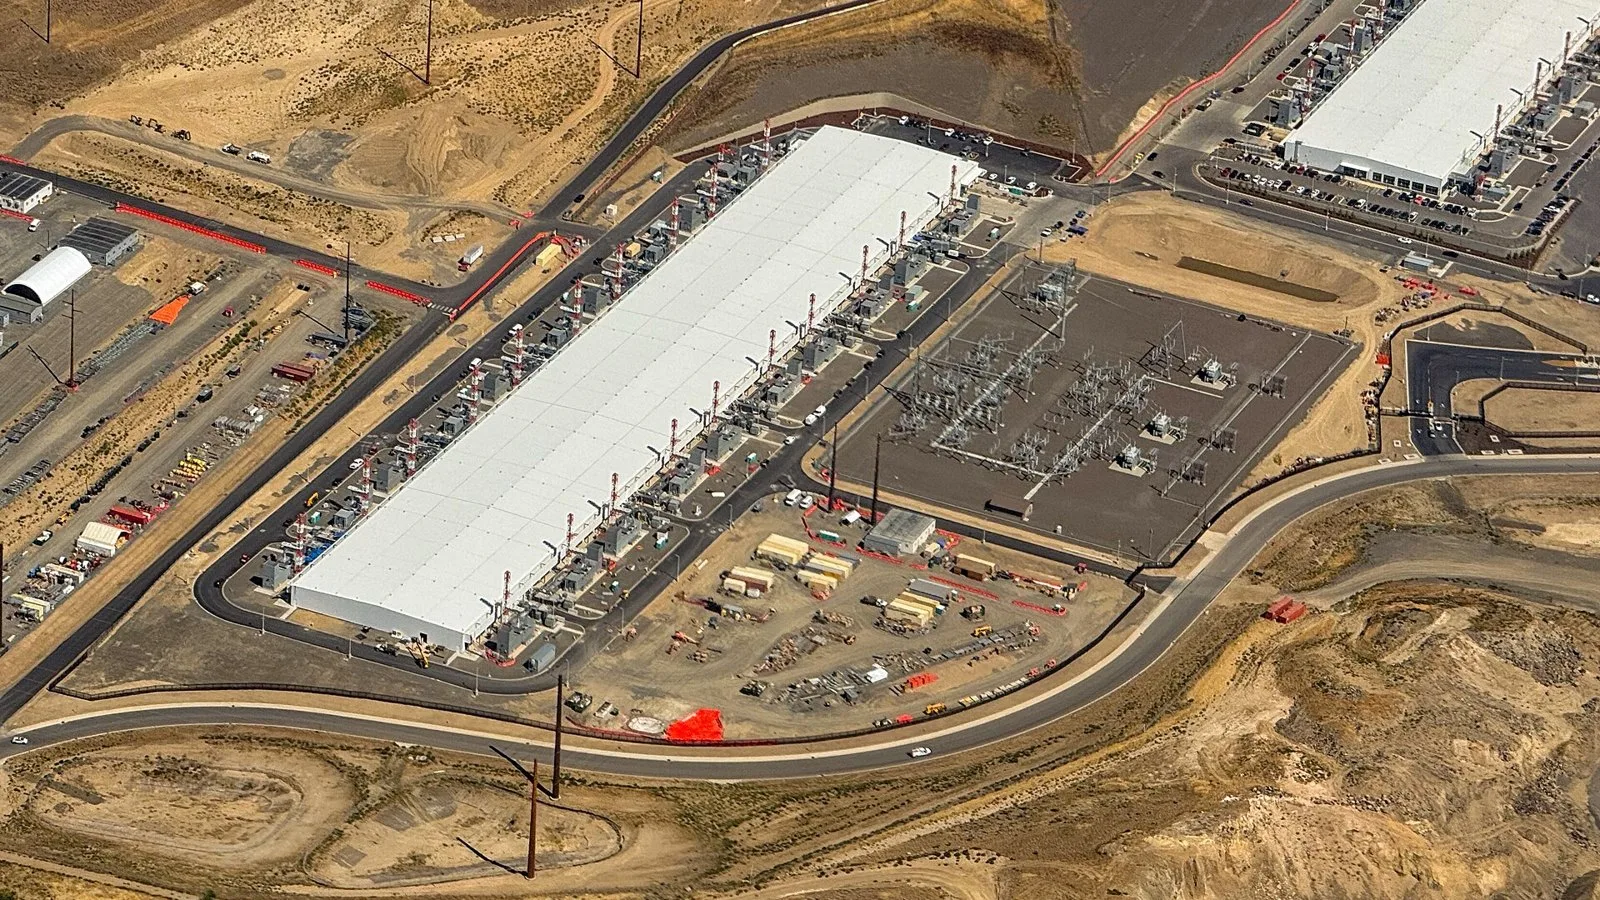
- The cash flow is the problem. Fiscal 2026 capital expenditure reached $115.95bn, up 79.62% year over year, with calendar-2026 spending expected around $175bn. Fourth-quarter free cash flow fell 23.2%.
- The backlog is enormous and concentrated. Commercial remaining performance obligations stand at $678bn, up 84%, with a weighted-average duration of 2.3 years. Stripping out OpenAI, that backlog still grew 25% last quarter.
- A fresh broker note landed this morning. BNP Paribas analyst Stefan Slowinski reiterated a positive view with a $549 target on 23 September after meeting Microsoft’s investor relations team, arguing that Azure’s higher pricing on renewing contracts is a growth lever not yet visible in reported revenue.
What the last two sessions actually showed
Index-versus-stock comparisons are usually noise. Two consecutive sessions in which the gap runs the same direction, during a rally explicitly attributed to artificial intelligence, are harder to dismiss.
On Monday 21 September the Nasdaq-100 rose 2.83% to 30,482.35 – its first record close since early June – on a semiconductor rally and the reception to Meta’s Muse agent. Microsoft rose 1.59%, a little over half the index move. On Tuesday 22 September the index went on to a second record at 30,732.40, up 0.82%, and Microsoft went the other way, closing at $498.00 after giving up an intraday high of $508.50.
That is the whole tension in one line: the most valuable enterprise software franchise in the world, with the largest AI cloud backlog ever disclosed, declining on a day the AI index sets a record. We covered the index side of that move in our piece on the Nasdaq-100’s rebalance and the $22bn forced bid, and the editorial desk flagged the same divergence in Microsoft lagging the index again.
Why the market is discounting Microsoft
The explanation is not that Azure is slowing. Azure grew 43% in fiscal Q4 2026 and the company guided to roughly 45% constant-currency growth for fiscal Q1 2027 – an acceleration, not a deceleration, and the segment has now passed $100bn in annual revenue.
The explanation is what it costs to deliver that growth. Fiscal 2026 capital expenditure came in at $115.95bn, up 79.62% year over year, and calendar-2026 spending is tracking toward roughly $175bn. Free cash flow in the fourth quarter fell 23.2%. Across the hyperscalers, capital spending has climbed from around 70% of operating cash flow in 2025 to close to 100% in 2026, which is another way of saying that the cash these businesses generate is now almost entirely consumed by building the infrastructure.
Microsoft’s June was the sharpest expression of that repricing: the stock fell more than 20% in the month, its worst since December 2000, and its 52-week range now runs from $349.20 to $553.72. What changed in 2026 was not the demand signal but the market’s willingness to pay upfront for a three-to-five-year infrastructure build with messy free cash flow in the middle.
The backlog, and the concentration question inside it
Commercial remaining performance obligations of $678bn, up 84%, is the single most impressive number Microsoft discloses. It is contracted revenue the company has not yet recognised, with a weighted-average duration of 2.3 years.
The caveat that gets attached to it is customer concentration, specifically OpenAI, which is itself diversifying its cloud supply across several providers. The useful way to read the exposure is the figure Microsoft gives for the backlog excluding OpenAI: it still grew 25% last quarter. That is a genuinely healthy enterprise number, and it means the backlog does not depend on a single counterparty to keep growing – though it does mean a meaningful slice of the headline figure sits with one customer whose own commitments are in flux.
This is the same trade playing out across the complex from a different angle. The chipmakers get paid when the hardware ships; the hyperscalers buying it have to convert that hardware into profit afterwards. Our coverage of AMD’s run toward a $1tn valuation tracks the side of that trade the market currently prefers.
Scenarios into year-end
| Scenario | MSFT level | Anchor | What has to happen |
|---|---|---|---|
| Bear | $440 -11.6% from spot |
Lowest published target in the 55-analyst S&P Global poll | The 28 October results show capex rising again without a matching step-up in Azure revenue, free cash flow stays negative year over year, and the market extends the de-rating it began in June. |
| Base | $576 +15.7% from spot |
Consensus average target, 55 analysts (S&P Global) | Azure holds the guided 45% constant-currency pace, capex guidance stabilises rather than climbing, and the stock closes part of its 900 basis point gap to the S&P 500. |
| Bull | $650 +30.5% from spot |
Morgan Stanley target, which calls Microsoft a top pick | Azure renewal pricing lands the way BNP Paribas describes, the $678bn backlog starts converting visibly into recognised revenue, and the capex cycle is re-rated as an asset rather than a drag. |
Anchors are published analyst targets as cited, measured against the $498.00 close of 22 September 2026. Percentages are rounded. The single highest target in the S&P Global poll is $870 and the consensus across wider broker surveys runs slightly higher, near $589 to $592; both are outliers relative to the figures used above.
Quick Take
Microsoft is not being punished for missing. It has beaten on earnings repeatedly, Azure is accelerating into year-end, and the contracted backlog is the largest it has ever reported. It is being punished for the shape of the spending: roughly $175bn of calendar-2026 capital expenditure, free cash flow down 23.2% in the most recent quarter, and a payback that lands in 2027 and beyond. That is why the index can set records without it. The 28 October results are the first scheduled moment where the conversion either starts showing up or does not.
What to watch next
- Fiscal Q1 2027 results on 28 October – the first test of the roughly 45% constant-currency Azure guide and of whether capex guidance stabilises.
- Free cash flow direction – the 23.2% fourth-quarter decline is the number the de-rating is built on; a turn there matters more than the revenue line.
- Azure renewal pricing – the specific lever BNP Paribas argues is not yet reflected in reported revenue.
- OpenAI’s cloud diversification – it does not threaten backlog growth, which runs at 25% without it, but it shapes how the $678bn headline should be read.
Frequently asked questions
What is Microsoft’s stock price today?
Microsoft closed at $498.00 on 22 September 2026, down $3.61 or 0.72% on the day, and was quoted at $503.00 in pre-market trading at 9:08 a.m. ET on 23 September (StockAnalysis). Its 52-week range is $349.20 to $553.72.
Why is Microsoft stock underperforming the Nasdaq 100?
The market is discounting the cost of Microsoft’s AI build-out rather than its growth. Fiscal 2026 capital expenditure rose 79.62% to $115.95bn, calendar-2026 spending is tracking toward roughly $175bn, and fourth-quarter free cash flow fell 23.2%. Semiconductor suppliers get paid on delivery; Microsoft has to convert that hardware into profit later, and that conversion is still ahead of it.
Is Azure growth slowing?
No. Azure grew 43% year over year in fiscal Q4 2026, and Microsoft guided to roughly 45% in constant currency for fiscal Q1 2027. Azure passed $100bn in annual revenue for the first time.
What is Microsoft’s analyst price target?
The consensus rating is Strong Buy with an average target of about $576 across 55 analysts polled by S&P Global, implying roughly 16% upside from the 22 September close. The range runs from $440 at the low to $870 at the high. Recent individual targets include BNP Paribas at $549 (23 September), Wedbush at $625 and Morgan Stanley at $650.
How much of Microsoft’s backlog is tied to OpenAI?
Microsoft does not break out a customer-level figure, but it does disclose that commercial remaining performance obligations excluding OpenAI grew 25% last quarter, against 84% growth for the $678bn headline. That gap is the clearest public measure of the concentration.
When does Microsoft next report earnings?
Fiscal Q1 2027 results are scheduled for 28 October 2026.
Why did Microsoft have its worst month since 2000 in June 2026?
The stock fell more than 20% during June 2026 as investors repriced AI capital spending. Across the hyperscalers, capex moved from around 70% of operating cash flow in 2025 to close to 100% in 2026, leaving far less cash available for shareholders while the returns on that spending remain unproven.
Disclaimer: This article is for informational purposes only and does not constitute investment advice, a recommendation, or an offer to buy or sell any security. Investing in equities carries risk, including the possible loss of principal. Prices and analyst targets cited are as of the time of writing and will change. Always conduct your own research and consider consulting a licensed financial adviser before making investment decisions.