New York Bans Celsius Founder Mashinsky From Financial…
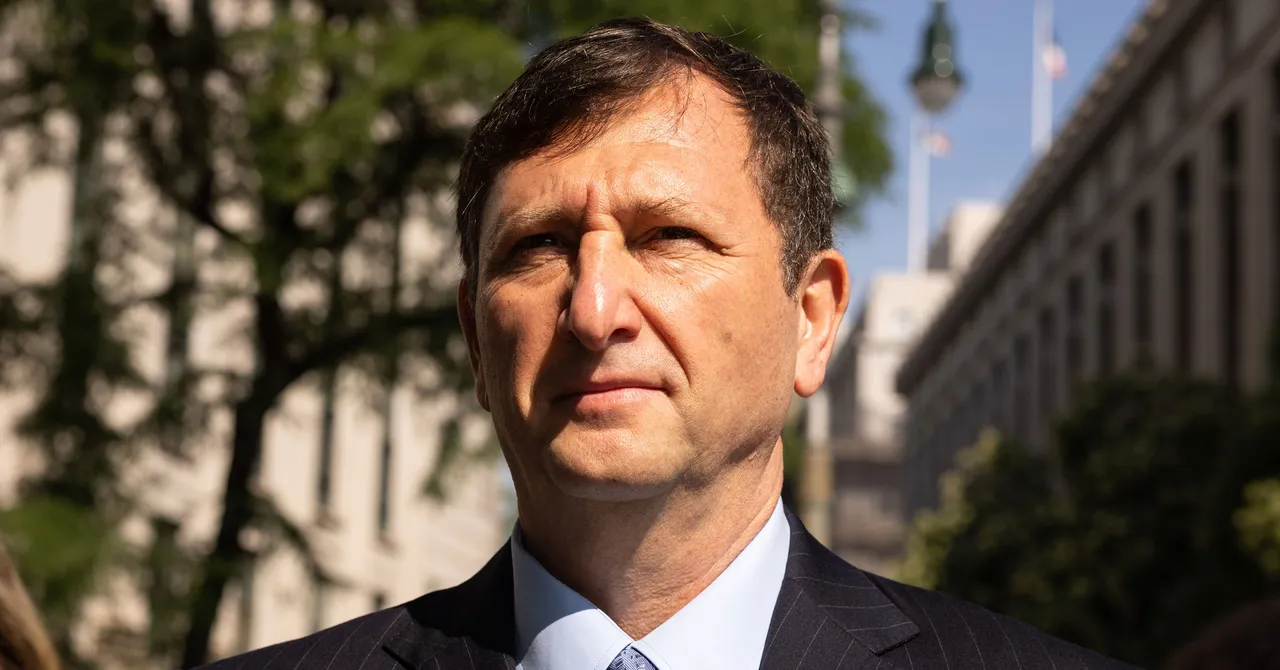
New York Attorney General Letitia James has secured a permanent financial-industry ban against former Celsius Network CEO Alex Mashinsky and a settlement carrying up to $35 million in conditional payments, according to a court stipulation published by the Attorney General’s office. The resolution adds a state-level enforcement outcome to the criminal prosecution, federal forfeiture proceedings and bankruptcy distributions arising from the collapse of the cryptocurrency lender.
Mashinsky, who is serving a 12-year federal prison sentence, is permanently barred from participating in the securities, commodities and cryptocurrency industries under the New York settlement. The financial provisions are structured around conditions involving federal forfeiture and the length of his imprisonment, rather than an immediate obligation to pay the entire $35 million.
How the $35 Million Settlement Actually Works
The settlement contains two separate conditional payment obligations. Mashinsky must pay $25 million to New York if he fails to forfeit an additional $10 million in illicit gains to the federal government, beyond assets already forfeited under his federal criminal agreement. A further $10 million payment becomes due if he does not serve his full prison sentence as mandated by the criminal court and administered by the Bureau of Prisons.
These provisions mean the headline $35 million figure is a maximum contingent amount, not a confirmed recovery already transferred to New York authorities. The conditions also distinguish this settlement from the more than $48 million Mashinsky was ordered to forfeit in the federal criminal proceedings.
New York’s action sits alongside a separate federal commodities enforcement case. The CFTC consent order involving Mashinsky illustrates how the collapse generated overlapping regulatory proceedings rather than a single enforcement action covering every aspect of the business.
The permanent prohibition is arguably the more consequential prospective remedy. Monetary penalties address past misconduct, while an industry ban restricts Mashinsky’s ability to return to regulated financial activities after imprisonment. Its practical scope will depend on the terms of the order and the activities covered by the relevant laws.
More Than $3.4 Billion Distributed Through Bankruptcy
Celsius creditors have received more than $3.4 billion through the company’s bankruptcy proceedings, according to the Attorney General’s office. Those distributions are separate from the New York settlement and the criminal forfeiture obligations.
That distinction matters when assessing recoveries from failed cryptocurrency platforms. Bankruptcy distributions generally arise from the administration and allocation of a debtor’s estate, while regulatory settlements and criminal forfeitures follow different legal procedures and may benefit different claimants.
The amount distributed also should not be confused with full compensation for every creditor. Individual recovery depends on claim classification, applicable valuation methods, distributions received and the relevant bankruptcy arrangements. A large aggregate distribution does not establish that investors recovered the full economic value of their original holdings.
The Federal Trade Commission separately obtained $16.5 million from Celsius founders and executives, adding another enforcement outcome to a case involving multiple agencies and legal frameworks.
How Celsius Sold Yield as Safety
Celsius attracted customers by offering yields on deposited digital assets. According to New York’s original enforcement complaint, Mashinsky promoted the platform as a comparatively safe destination for cryptocurrency savings while concealing the risks associated with its lending and investment strategies.
The Attorney General alleged that Mashinsky repeatedly portrayed Celsius as safer than a bank, despite the platform lacking the same prudential requirements, deposit protections and supervisory framework applicable to conventional banking institutions.
The alleged misconduct went beyond optimistic descriptions of investment performance. New York accused Mashinsky of misleading investors about the company’s safety, customer numbers and investment activities, while Celsius incurred substantial losses through risky strategies.
The case demonstrates a fundamental problem with the marketing of cryptocurrency yield products: the yield paid to depositors must ultimately be supported by economic activity, such as lending, investment returns or other revenue. When the underlying strategy involves credit exposure, leverage, maturity mismatches or concentrated counterparties, a seemingly straightforward deposit product can carry risks that are difficult for customers to observe.
Unlike a bank deposit, a cryptocurrency lending account does not automatically carry deposit insurance or the protections associated with regulated banking. The legal rights of customers also depend on contractual terms governing custody, ownership and the use of deposited assets.
New York’s Enforcement Strategy Extends Beyond Celsius
The Mashinsky settlement forms part of a broader series of cryptocurrency enforcement actions by the New York Attorney General. These include a $200 million settlement with Galaxy Digital concerning Luna-related conduct, proceedings involving NovaTechFx and AWS Mining, and action against Uphold over its promotion of investments associated with the failed lender Cred.
The cases differ substantially in their allegations, legal outcomes and affected investors. Their common regulatory theme is the application of existing investor-protection and anti-fraud laws to cryptocurrency businesses, even when those businesses operate through technologies or structures not contemplated when the statutes were enacted.
For cryptocurrency lenders and exchanges, the enforcement history highlights the importance of distinguishing custody services, lending arrangements, investment management and deposit-like products. Each can create different obligations concerning disclosure, registration, customer assets and conflicts of interest.
The Celsius proceedings also show that regulatory exposure does not necessarily end when a platform enters bankruptcy. Former executives may face personal civil, criminal and administrative consequences independently of the corporate restructuring process.
What the Case Means for Crypto Investors
The final settlement does not establish that every cryptocurrency yield product is unlawful or that every platform offering returns operates fraudulently. It does, however, reinforce the distinction between a promised return and the financial arrangements required to generate it.
Investors evaluating lending platforms need to understand whether deposited assets remain segregated, whether the provider can rehypothecate them, what counterparties ultimately receive the funds and how withdrawals would be handled during a liquidity crisis.
For the industry, Mashinsky’s permanent prohibition closes another part of the Celsius enforcement process. For creditors, the more immediate financial question remains the value of bankruptcy recoveries and any further distributions available under the relevant proceedings.